Your recipe cards say 28%. The month-end close says 31.5%. In between sit three and a half points of food cost that nobody decided to spend. The gap between actual and theoretical food cost is one of the most revealing numbers a kitchen produces, provided you know how to calculate it and, above all, how to read it.
Theoretical vs actual food cost: two numbers, two methods
Both ratios measure the same thing, the share of food sales spent on ingredients, but they start from different data.
| Theoretical food cost | Actual food cost | |
|---|---|---|
| Question | What the kitchen should have used | What it actually used |
| Data | Sales per dish × cost of each recipe card | Opening stock + purchases − closing stock |
| Sources | Till (EPOS) and recipe cards | Invoices and stocktakes |
| What it ignores | Waste, over-portioning, errors, anything that leaves unsold | Why the gap exists |
Theoretical food cost adds up, for every dish sold, the cost on its recipe card, then divides by net food sales. It is what you would have spent if every plate had been made exactly to spec, with no waste and no mistakes. Actual food cost starts from consumption: what was in stock, plus what was bought, minus what is left. Both formulas are set out in our guide on how to calculate food cost.
Calculating food cost variance: an example
Take a hypothetical month with net food sales of 120,000.
| Dish | Portions sold | Recipe card cost | Theoretical cost |
|---|---|---|---|
| Dish A | 1,200 | 5.10 | 6,120 |
| Dish B | 900 | 7.40 | 6,660 |
| Dish C | 1,500 | 3.20 | 4,800 |
| Rest of the menu | — | — | 16,020 |
| Total | 33,600 |
Theoretical food cost: 33,600 ÷ 120,000 = 28.0%.
On the actual side: opening stock of 15,000, purchases of 37,200, closing stock of 14,400. Food used comes to 37,800, an actual food cost of 31.5%.
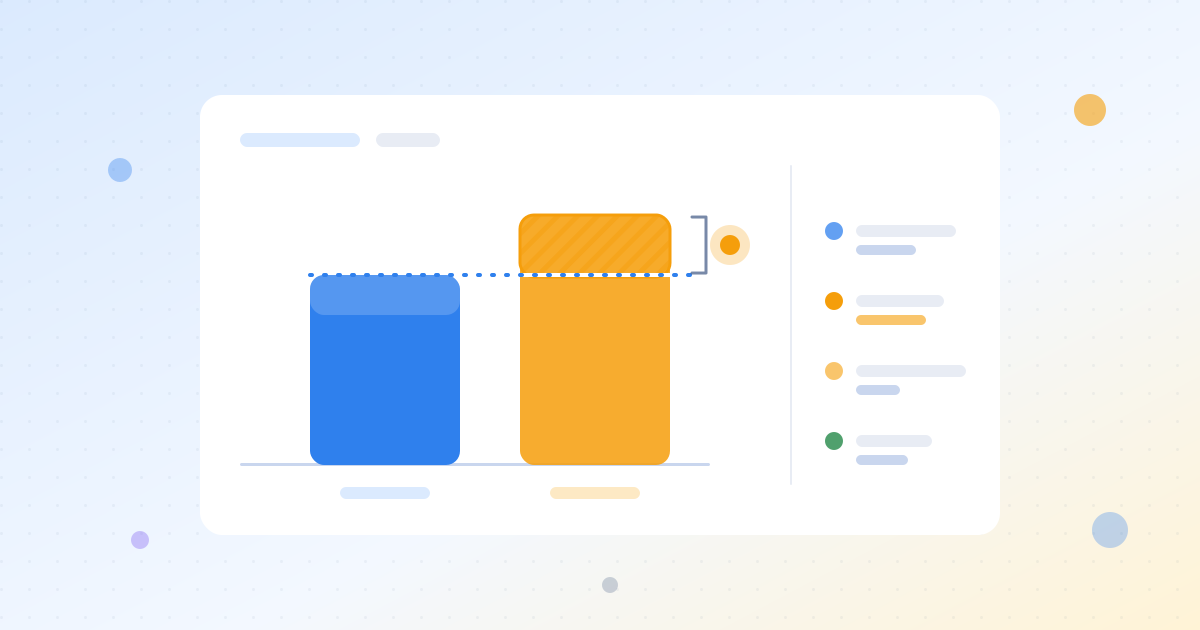
The food cost variance is 3.5 points, or 4,200 by value over the month. Keep the value figure in mind: one point of food cost does not weigh the same in a neighbourhood bistro and in the brasserie of a large hotel.
Where the gap comes from
Recipe cards that are wrong or out of date
Theoretical cost is only as good as the recipe cards. A recipe changed in the kitchen but not on paper, an extra garnish, a new supplier: the theoretical figure describes a dish that no longer exists. Our recipe costing sheet template helps keep them current.
Purchase prices that have moved
This is the most underrated cause. If recipe cards are costed with prices from six months ago, every increase since then shows up as variance. Teams go hunting for waste in the kitchen when the real culprit is price drift.
Portioning
A few extra grams on a steak or a portion of chips, repeated over hundreds of covers, is enough to widen the gap. Without scales or a visual standard at the pass, portions drift with fatigue and the rush.
Waste and spoilage
Out-of-date stock, prep binned at the end of service, cooking mistakes, breakages in the store: everything that goes in the bin is consumed without being sold. Our article on reducing food waste in restaurants covers the purchasing side of the problem.
What leaves without being sold
Staff meals, comps, tastings, transfers to the bar, room service or banqueting: these movements add to consumption without showing up in the kitchen’s sales. In a hotel where several outlets draw on the same stores, they can explain a large part of the gap.
Receiving and invoicing errors
A case invoiced but never delivered, a weight below what was declared, a price above the agreed rate: actual food cost records the spend, theoretical cost does not. See the supplier invoice errors you’re paying for.
Stocktakes and the till
A miscounted or badly valued stocktake distorts actual food cost directly. Dishes rung through under the wrong button distort the theoretical figure. And a stocktake done on the 3rd for sales closed on the 30th puts the two periods out of step.
Splitting the price effect from the quantity effect
Before looking for culprits, one simple step changes everything: re-cost the theoretical figure at the latest prices paid. In our example, the same sales valued at this month’s prices come to 35,400, or 29.5%. The variance now splits in two:
- price effect: 35,400 − 33,600 = 1,800, or 1.5 points. Not a kitchen problem: a purchasing problem, or recipe cards that need updating;
- quantity effect: 37,800 − 35,400 = 2,400, or 2 points. This is where you look at portions, waste, unsold movements and the stocktake.
The next step is to drill down to product level on your most expensive lines. If the month’s sales justify 42 kg of beef fillet and stock movements show 48 kg used, the missing 6 kg is a specific issue, not a hunch.
| Symptom | Likely cause | What to check |
|---|---|---|
| Variance tracks price rises | Recipe cards costed at old prices | Card prices vs latest prices paid |
| Variance concentrated in one category (meat, fish) | Portioning, trim, waste | Portion weights, yields, bins |
| Variance swings month to month | Stocktake or period mismatch | Count dates, valuation |
| Variance grows with events | Transfers and unsold movements | Requisitions, internal recharges |
| Variance tied to one supplier | Receiving or invoicing | Delivery notes, agreed prices |
What level of variance is acceptable?
There is no universal threshold: it depends on your concept, how much raw produce you prepare on site and how rigorous your counts are. Set your own tolerance and watch the trend. A stable gap can be managed; a gap that grows month after month means a new cause has taken hold.
Six steps to reduce food cost variance
- Cost recipe cards at the prices you actually paid. Otherwise you are hunting for waste that is really price inflation.
- Align periods and scopes. Stocktake on the day sales close, kitchen separate from bar, a ratio per outlet.
- Record unsold movements. Staff meals, comps and transfers logged, even simply.
- Check deliveries on arrival. Quantities and weights against the delivery note and the order, prices against the agreed rate.
- Count expensive lines more often. A rolling count on your costliest products helps pinpoint the gap. Our restaurant inventory method explains how to organise it.
- Standardise portions. Posted portion weights, portioning tools, plating photos.
Bringing purchases, stock and recipes together with Eqolux
Measuring the gap needs three building blocks that rarely live in the same place: recipe cards at today’s prices, properly valued stocktakes and sales per dish.
With Eqolux menu engineering, recipe cards are costed with the prices you actually paid and recalculated with every new invoice, so the price effect no longer hides among the losses. Sales are imported with the Eqolux Excel template, and menu prices are set by outlet and by service. With Eqolux inventory, counts are organised by zone with the catalogue as backbone, and each item is valued at its latest real purchase price. Reconciling purchases, stock and actual consumption shows you the shrinkage and the recipes that are drifting.
Key takeaways
- Theoretical food cost = sales per dish × recipe card costs; actual food cost = opening stock + purchases − closing stock. Both divided by net food sales.
- Food cost variance is read in points and by value.
- Re-costing the theoretical figure at the latest prices paid separates the price effect (purchasing) from the quantity effect (kitchen, waste, stocktake).
- Then drill down to product level on your most expensive lines.
Want to reconcile your recipes, stock and real purchases? Explore Eqolux inventory or book a demo on your own data.